INTEGRIS provides actuarial, compliance, registration, and administration services. MacNicol & Associates Asset Management manages the pension assets using an institutional, multi-asset approach.
THE OPPORTUNITY
Retained earnings can work harder.
For incorporated professionals and business owners, three structural issues can reduce the efficiency of long-term wealth accumulation:
01 Passive corporate income
Passive investment income retained in a corporation can face an effective tax burden approaching 50% once integration is considered.
02 RRSP limits
RRSP contribution room is capped. A registered Personal Pension Plan can create materially more deductible funding room, particularly at older ages and for longer-service employees.
03 Estate taxation
An RRSP or RRIF is generally included in income at death unless a qualifying rollover applies. Pension benefits can offer different continuation and estate-planning outcomes, subject to plan terms and tax advice.
Existing tax law. Applied intelligently.
- Potentially greater contribution room: $93,595 versus $33,810 at age 60 in the illustration.
- Employer-funded, tax-deductible contributions within a CRA-registered pension structure.
- Creditor protection and pension-grade investment access, subject to applicable law and plan terms.
- INTEGRIS manages the actuarial, regulatory, and administrative work; MacNicol manages the investment portfolio.
Illustrative 2026 base
The examples use T4 employment income of $196,611—salary or bonus paid by the corporation, not total compensation. Final figures depend on age, service history, compensation, plan design, and actuarial valuation.
CONTRIBUTION CAPACITY
More room as retirement approaches.
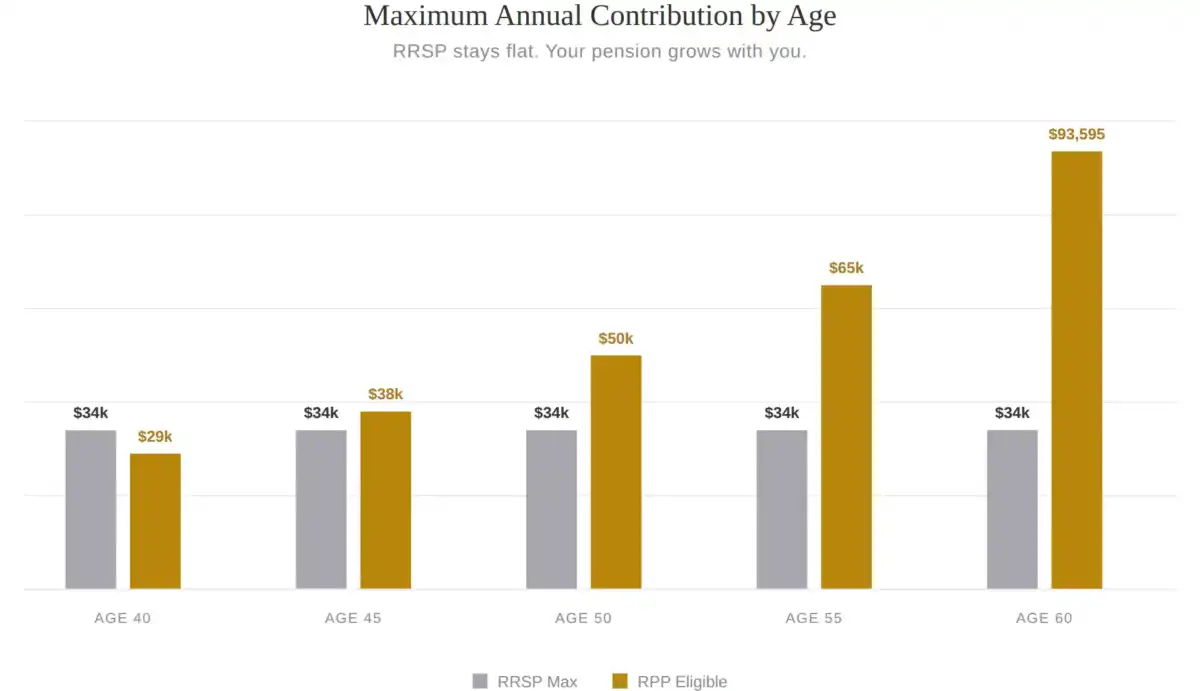
Unlike the flat RRSP ceiling shown here, eligible pension contributions can rise with age and actuarial funding requirements.
At age 60
$93,595 of illustrated pension contribution room compared with $33,810 of RRSP room—approximately 2.8 times as much.
Illustrative annual contribution room. RRSP values are shown at $33,810; pension eligibility varies by age.
The contribution amounts at ages 40, 45, 50, and 55 are illustrative. A personal actuarial valuation is required before any funding decision.
PLAN DESIGN
One coordinated structure.
The corporation sponsors and deducts contributions to a registered pension plan. INTEGRIS handles plan design and ongoing administration, while MacNicol manages the institutional portfolio.
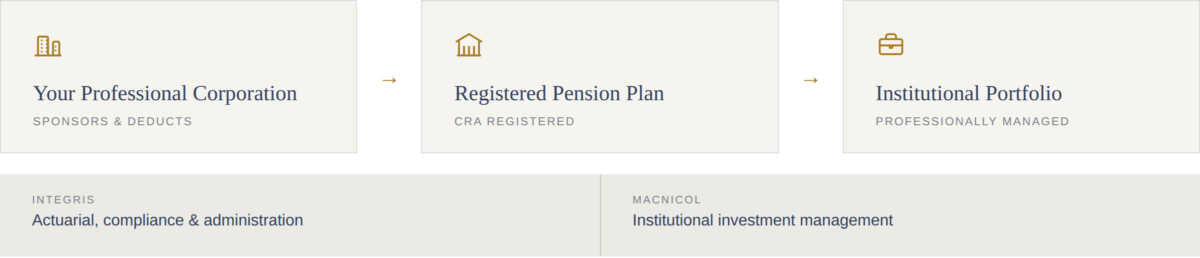
A coordinated relationship among the sponsoring corporation, the registered pension plan, INTEGRIS, and MacNicol.
Four steps. Fully managed.
1. The corporation sponsors
The owner’s corporation establishes the pension plan as the employer.
2. The plan is registered
The IPP or PPP is registered with the Canada Revenue Agency and designed around the member’s facts.
3. INTEGRIS administers
Actuarial work, compliance, registration, annual filings, and plan administration are handled by INTEGRIS.
4. MacNicol invests
MacNicol manages the pension assets using strategies and portfolio tools normally associated with larger institutional plans.
PERSONAL PROJECTION
See the difference for yourself.
The calculator compares projected pension savings with an RRSP using age, current T4 salary, past T4 service, average past T4 salary, and—optionally—an existing RRSP balance.
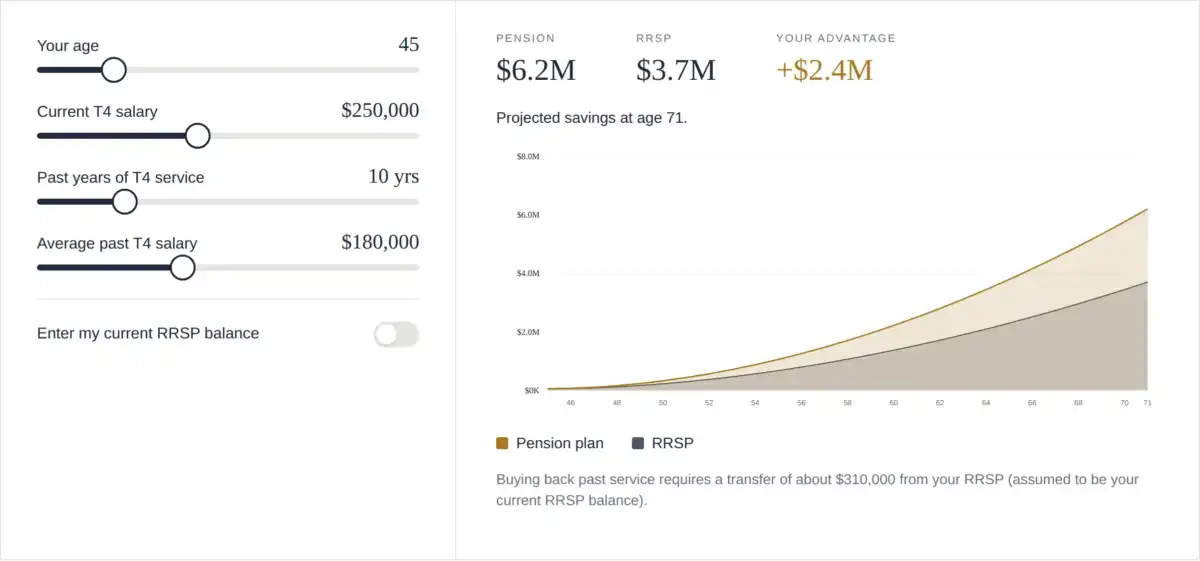
Example calculator output. Estimates are illustrative and do not replace a personalized actuarial illustration.
Example shown
At age 45, with $250,000 of current T4 salary and 10 years of past service, the example projects $6.2 million in pension savings versus $3.7 million in an RRSP by age 71. Results change with every input and are not a guarantee.
CALCULATOR EMBED
Official INTEGRIS embed code
INTEGRIS publishes the following iframe pattern for a Personal Pension Plan calculator. The cta=off parameter hides the INTEGRIS call-to-action so a separate page-level call-to-action can be used.
<iframe
src=”https://integris-mgt.com/calculatorskinny?cta=off”
width=”100%”
height=”700″
title=”INTEGRIS PPP Calculator”
loading=”lazy”
style=”border: 0;”
></iframe>
Optional IPP presentation: use https://integris-mgt.com/calculatorskinny?plan=ipp&cta=off. That version uses IPP labels and restricts the age slider to 40+.
Developer documentation: integris-mgt.com/developers/
Implementation note
Browser framing policies can affect third-party iframes. Confirm the embed on the intended live domain. INTEGRIS also documents a numerical projection endpoint for teams that need a custom interface. Never transmit personal information to the projection endpoint.
FAMILY CONTINUITY
A different conversation at death.
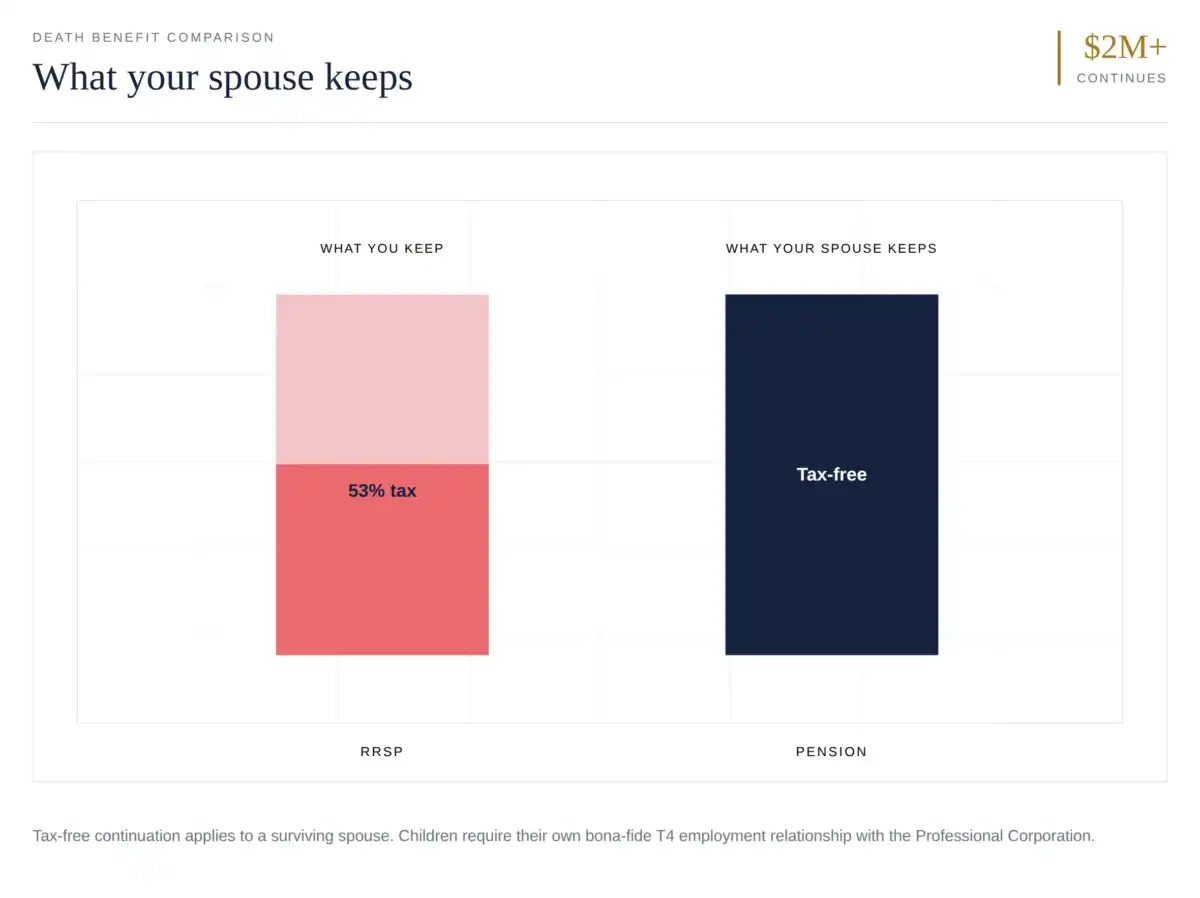
Pension benefits can provide continuity for a surviving spouse rather than forcing the same immediate tax outcome associated with an RRSP or RRIF.
Important family-member distinction
Tax-free continuation applies to a qualifying surviving spouse under the plan rules. Children may participate as plan members only where they have a bona-fide T4 employment relationship with the sponsoring corporation. Treatment otherwise differs and requires individual tax and legal advice.
Illustrative comparison
On a $2 million RRSP balance, a 53.53% terminal tax rate would leave approximately $1.07 million. A pension may continue benefits to a qualifying surviving spouse, subject to the plan terms and applicable law.
INVESTMENT MANAGEMENT
MacNicol: compounding without the whiplash.
MacNicol & Associates Asset Management brings more than 25 years of private-wealth experience and over $1 billion in assets under management and advisory. The firm is independent and owner-operated, with no house products.
A track record, not a pitch deck
Capital managed through 2008, 2020, and 2022 provides experience across very different market environments.
Lower volatility by design
A multi-asset allocation may combine equities, real assets, private capital, and portfolio insurance to help reduce drawdowns and support steadier compounding.
Pension-grade access
The plan can access strategies and portfolio construction methods typically associated with institutional investors.
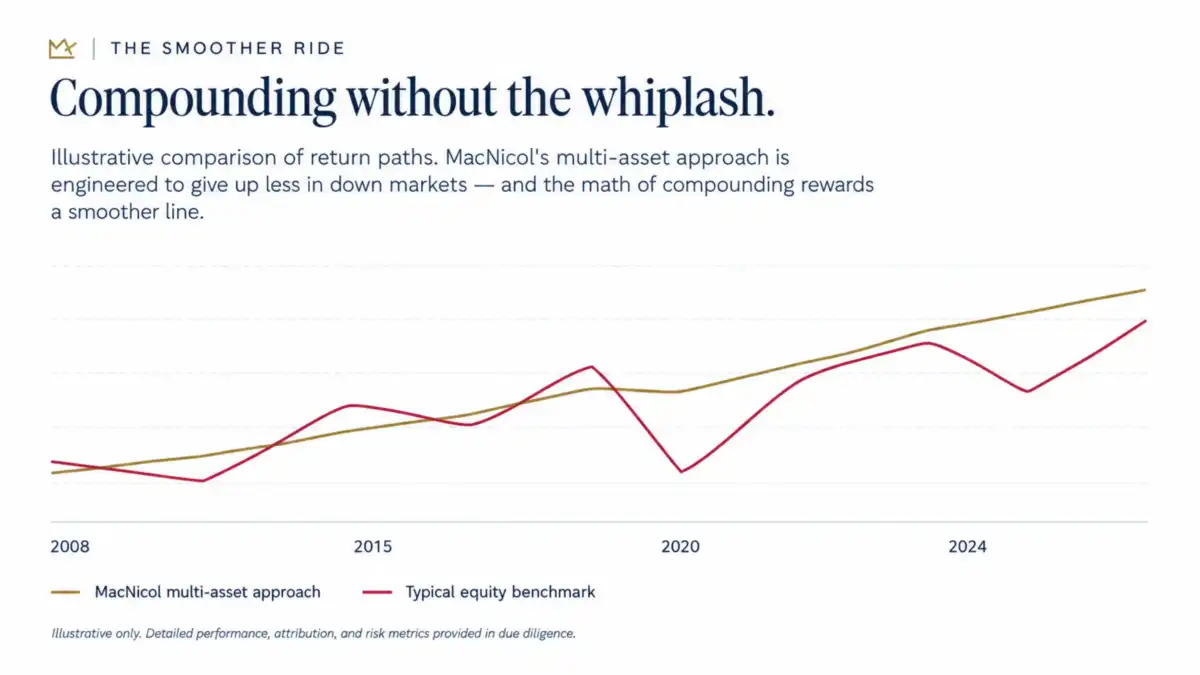
Illustrative only. This graphic is not a presentation of fund or mandate performance. Detailed performance, attribution, and risk metrics are provided during due diligence.
WHY THE PARTNERSHIP MATTERS
Specialists at every stage.
INTEGRIS Pension Management
- Plan design and actuarial valuation.
- Registration, compliance, and annual administration.
- A personalized illustration based on the member’s age, T4 compensation, service, and retirement objectives.
MacNicol & Associates Asset Management
- Institutional portfolio management for pension assets.
- Independent, owner-operated investment oversight.
- A multi-asset approach intended to balance growth, downside protection, and long-term compounding.
Shared objective
Create a professionally governed retirement structure that can improve tax efficiency, increase retirement funding capacity, and support intergenerational planning—without asking the sponsoring business to become a pension administrator.
Next step
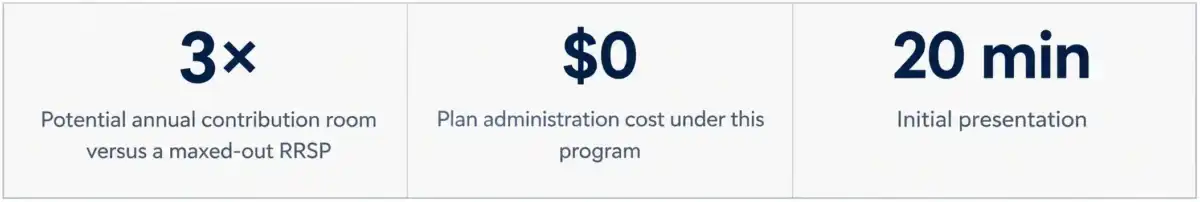
Book a 20-minute presentation to review fit, estimated contribution room, past-service opportunities, administration, and investment due diligence. No cost. No obligation.
*Required Fields
MacNicol & Associates Asset Management will not share your information. For information on how we use your personal information, please refer to our Privacy Policy
Personal Pension Plan overview prepared from the current pension-page content. “PPP” and “IPP” terminology should be confirmed for the intended audience and final plan design.
This material is for discussion purposes only. It is not tax, legal, actuarial, or investment advice; figures are illustrative and not guaranteed. Eligibility, contribution limits, deductions, creditor protection, survivor benefits, and estate outcomes depend on individual facts, governing legislation, plan terms, and professional advice.